Firmus launches what looks to be a great financial bubble
Written by: Nick G. on 8 October 2026
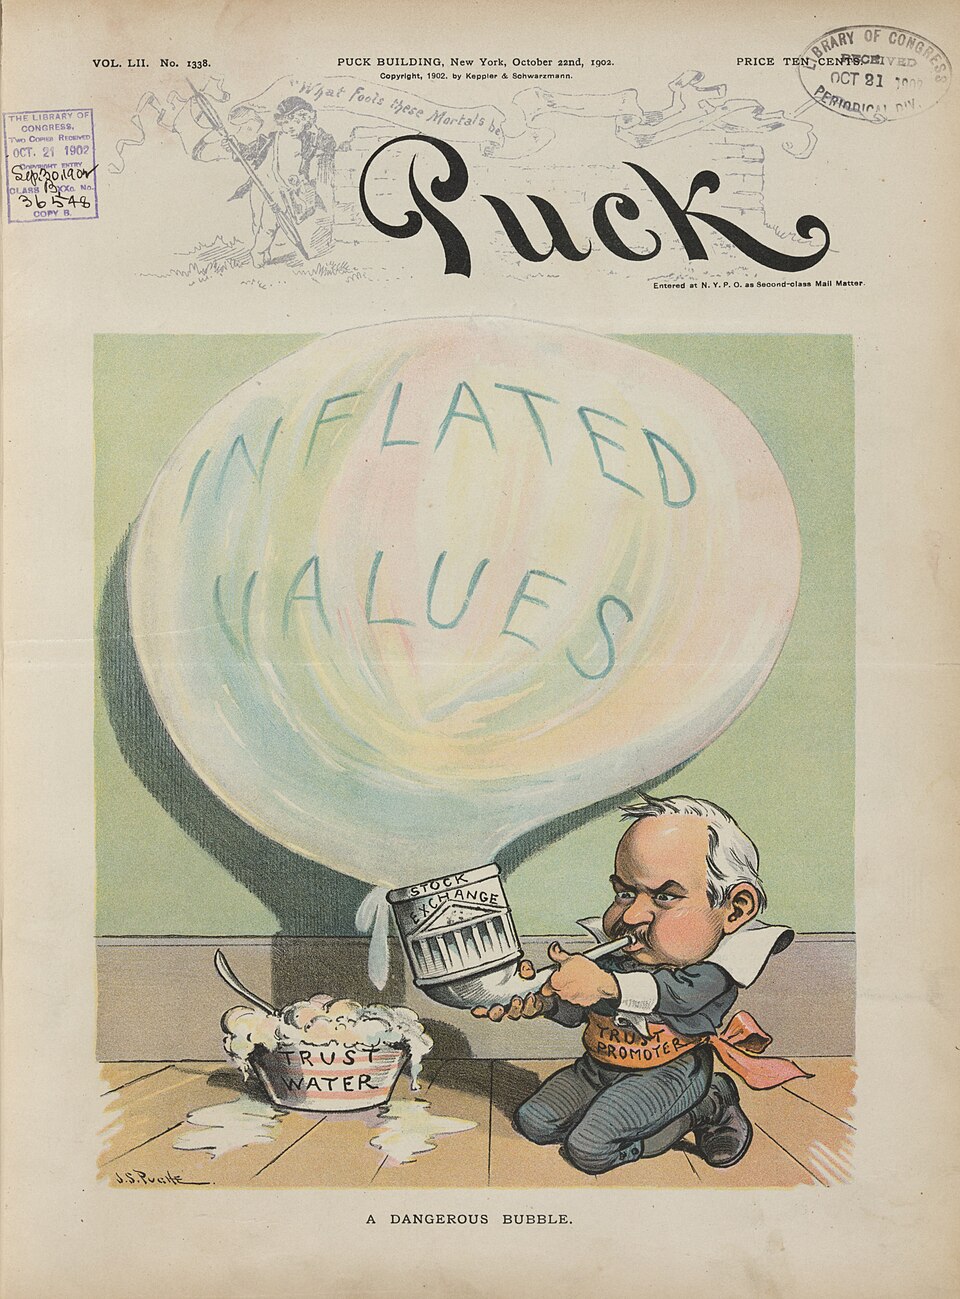
(Above: The dangerous bubble. Puck magazine 22 October 1902 Public domain image)
On October 6, Australian data centre company Firmus launched its initial public offering (IPO) of shares for private investors, taking the privately-owned company into the public sphere. It valued its shares at $A11 each, in what the Australian Financial Review called, on October 6, “hottest float headed to the ASX in more than two decades”. The company is hoping to raise $A7 billion from those buying its shares.
The IPO closed on October 8, and Firmus will begin trading on the ASX on October 23.
Firmus and the creation of surplus value
What does Firmus do, and how can investors feel confident to claim their share of future surplus value when Firmus products, which contain surplus value created by human labour power embedded in the production process, are turned into profit realised through sales?
Marx’s explanation for the value of products was that workers had to work part of their day to create in the product the value that was necessary for the employer to pay their wages, but that any time surplus to that requirement, that is the additional hours of the working day, resulted in workers creating a surplus value for which they were not paid. This surplus value was left over from the need for the employer to cover the cost of their wages, and was the source of a company’s profits when those products were sold.
When automation is taken to its extreme, robots and other components of production, driven by AI programs, obviate the need for much, if not all, human labour power. Marx predicted this in his late 1850s unfinished manuscript on political economy called “The Grundrisse”, where he predicted the situation where, through automation, “the value-creating power of the individual labour capacity is an infinitesimal, vanishing magnitude…”
So, how does a data company like Firmus, create surplus value, and hence profits for its shareholders?
What do data factories make?
Firmus is something a little more than a data centre. The latter are large pieces of physical infrastructure which store, process and transmit data at a huge cost in energy and water (for cooling).
What Firmus operates are data factories (in some parlance, referred to as AI factories), large pieces of physical infrastructure which transform data into products, particularly AI models, predictions, tokens for cryptocurrency mining, and generated content. They also consume huge amounts of energy and water.
A data factory does more than store and transmit data; it organises data for the production of artificial intelligence on a huge scale.
Unlike a data centre, which requires servers and storage facilities, a data factory requires huge numbers of graphics processing units (GPUs), specialized electronic circuits designed for digital image processing, and accelerators to speed the process, enabling them to perform billions of calculations in the proverbial blink of an eye. A data factory Firmus proposes to build on Batam Island, Indonesia, designed to house up to 170,000 Nvidia GPUs.
What it doesn’t require much of in its production process is human labour power as Marx foretold in The Grundrisse.
But it is axiomatic in Marxist political economy that only human labour power is the source of surplus value, and hence of profit.
What does human labour power contribute to a data factory production process?
Why then run a data factory, or rush to invest in one?
While it may appear that machines do all the work, there is still a component of human labour power distributed throughout the system that contributes to the final product of a data factory.
Some of that is directly applied, for example, technicians who install and repair equipment, workers who ensure electricity supply and maintain associated infrastructure, and even “front of house” workers engaged in customer relations. There are also operators who monitor AI systems (the latter may soon include legislatively required independent or third-party evaluators whose role will be to “ensure that humans stay in control”). These are all applications of living human labour power.
There is also a component of (intellectual) human labour power that has already been used up in systems design, software program development, research and design of AI models, and related pre-production tasks, and although their labour power has already been used up and is theoretically “dead”, its value is embedded in its products and services and transmitted through them to data factory products.
This “dead” labour is transmitted to a product when living labour arranges its participation in the process of production. The constant capital (machinery, robots etc) transfers its value to the product through wear and tear, mediated by living labour. It transfers, but does not create. The amount transferred in a given production period is determined by the wear and tear of the constant capital — its depreciation over its useful life. If a machine is worth $1,000,000 and produces 100,000 units over its life, roughly $10 of its value enters each unit (ignoring moral depreciation, interest, etc.).
As with all applications of machinery since the capitalist destruction of hand manufacturing, the more that machinery and the less that human labour power are applied in production generally results in greater efficiency and greater productivity but, over time, lower sales volume can result if the market of wage workers is increasingly impoverished.
In the long run (even in the short run when bubbles burst) producing a hundred times more of a product does not mean the production of a corresponding scale of value. Greater productivity can result in products of lesser value if there is less input from human labour power producing surplus value. This can be compounded when competitors flood the market with the same or similar products at a reduced price.
Prices (as distinct from value) may be artificially maintained for a time by monopoly control of production (whether by copyright protection or buying out of competitors), or by breaking into new markets.
Gambling with fictitious capital until the bubble bursts
Those institutional finance capitalists (approximately 50% of the IPO is reserved for existing investors including Nvidia and Blackstone) and “mum and dad” investors who have bought into Firmus and have a claim on its future surplus value may have stopped using their capital as a non-productive “hoard”, but only through a process that separates their capital from production, rendering it a “fictional” or “virtual” capital so long as surplus value has not yet been created.
When it is, there will be a period when speculation will enable a return on investment, but it is always a gamble.
The gamblers run the risk of being deceived by the promise of production on scale, unaware that increased productivity does not necessarily create increased value, but rather, can create its opposite.
In that respect, Reserve Bank governor Michele Bullock was correct to warn that the AI investment boom, which includes data centres (and we use it here as a generic term for data/AI factories as well) “could be a bubble”.
She was echoing the views of the General Manager of the Bank for International Settlements (the “reserve bank” of central reserve banks), Pablo Hernández de Cos, who said in an interview with India’s Economic Times on September 11, 2026 that “the AI investment boom may become unsustainable. The reasons are two-fold.
“On the one hand, like many previous technology booms, there has been a race among firms to capture and obtain market share. This naturally leads to a certain degree of overinvestment. By definition, if there is overinvestment, that can also be a source of a bust at some point, particularly if returns disappoint.
“The second is related to the fact that the capital expenditure behind the AI investment boom is increasingly reliant on debt and leverage. An important element is that there are also relatively opaque private-credit structures and circular financing arrangements that create very complex interdependencies. So, if there is a disappointment in returns, we might have a bust in investment and this could be amplified by these financial channels. Why is this important? It is important per se, but also because, as we all know, the AI investment boom has been critical for the resilience of the global economy in recent years.”
We would not expect that general manager of the BIS to express such a warning in Marxist terms. But it is a warning none the less.
And an AI bubble will not be restricted to AI but will affect the “resilience of the global economy” for years.
This is also the view of AI analyst Will Lockett who wrote on October 1:
AI companies are burning cash at a furious rate, have racked up an astronomical amount of debt, have almost entirely exhausted all private funding routes, and have no viable path to profitability. This is a recipe for imminent bankruptcy, triggering a financial crisis through a massive debt default. This is why all of the AI labs are rushing to form IPOs, because going public is the last pool of money capable of fending off this collapse for at least a year or two.
The rush to IPOs began in spectacular fashion last June when Elon Musk’s SpaceX became the largest ever IPO, at a valuation of US$1.77 trillion. By late July 2026, SpaceX shares had fallen approximately 50% from their peak reached during the week after the IPO, causing Musk to lose his trillionaire status.
Applying for a listing on the New York Stock Exchange is Nscale, a European-based data factory created by Joshua Payne, an Australian former coalminer and construction worker. The company hopes to raise $US35 billion through its IPO.
Both OpenAI and Anthropic are lining up for IPOs.
However, investors are already sounding the alarm bells on Firmus, whose founder Oliver Curtis was jailed in 2016 for two years for insider trading on derivatives. On October 6, the Stocks Down Under website warned investors in an article titled “Why we wouldn’t touch the Firmus IPO with a 10-foot pole”.
The latest news is that there has been a failure to attract the predicted capital, and Firmus may have to lower its share price to around $8 in an effort to get more people on board.
Just like pumping air into a balloon eventually causes it to explode, so the pumping of cash into AI IPOs is heading for a bursting, and Firmus might just lead the way.
Print Version - new window Email article
-----
Go back
Independence from Imperialism
People's Rights & Liberties
Community and Environment
Marxism Today
International
Articles
| Firmus launches what looks to be a great financial bubble |
| Firming up on fictitious capital – Firmus and its capital raising |
| Party’s discussion paper published |
| Notes on Barbarism – The Manifestation of Barbarism with the Decline of US Imperialism |
| Articles by Ted Hill now on our website |
| Financialisation: fictitious capital and its real impact |
| BOOK REVIEW-: The AI Con: How to Fight Big Tech’s Hype and Create the Future We Want |
| BOOK REVIEW—The Eye of the Master: A Social History of Artificial Intelligence |
| Three lies about value |
| US Department of War releases Strategy Document |
| Adventurist Class War Rejecting the Working Class |
| Productivity: of what? from whom? for whom? |
| More on Imperialism and Religion |
| Imperialists used religion to justify their actions |
| Building a New Socialist Society |
| The “three constantly read articles” should still be constantly read. |
| Two new publications to promote study and guide practice |
| Reply to a reader |
| Criticising Xi Jinping Thought |
| BOOK REVIEW---CULTURE IS NOT AN INDUSTRY |
-----